Bonds
A bond is a loan with a price tag that moves. You lend Rs 1,000 to a government or a company, it pays you a fixed coupon every year, and it returns the Rs 1,000 at the end.
The mechanics, once
Three things are fixed when a bond is issued. The face value, usually Rs 1,000, which is what you get back at maturity.
The see-saw that matters
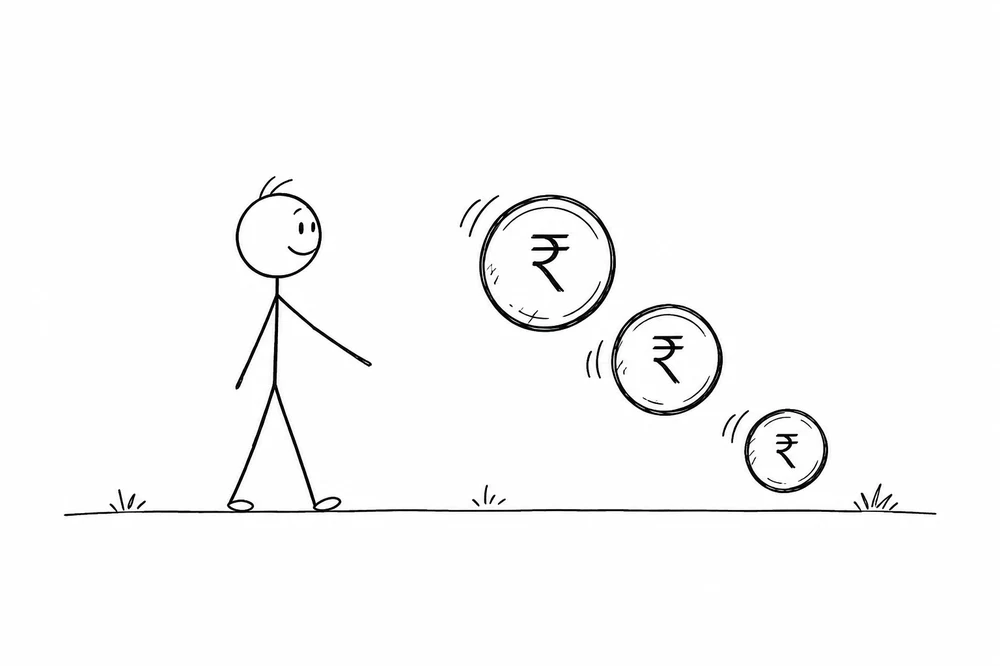
Here is the mechanism worth burning into memory. Suppose you hold a bond paying 7% and new bonds are now being issued at 8%.
What this means in practice
My rule of thumb is one question: will I hold this to maturity? If yes, buy the bond or the gilt fund matched to your horizon and ignore the daily price noise; your return was decided the day you bought.
A bond is a loan with a price tag that moves. You lend Rs 1,000 to a government or a company, it pays you a fixed coupon every year, and it returns the Rs 1,000 at the end. Simple enough that most explanations stop there. But the one thing that actually costs people money is the part they skip: between the day you buy and the day it matures, that “fixed income” instrument has a market price, and the price moves in the opposite direction to interest rates. In September 2026 the 10-year government bond yields about 7%. If rates rise one percentage point, that bond loses roughly 7% of its market value. Fixed income, variable price.
The mechanics, once
Three things are fixed when a bond is issued. The face value, usually Rs 1,000, which is what you get back at maturity. The coupon, the annual interest as a percentage of face value, which is where the “7% bond” language comes from. And the maturity date, when the loan ends. Who is borrowing decides the safety: a Government of India bond is the benchmark against which every other borrower in the country is priced, and everyone else, states, PSUs, companies, pays a premium over it for their extra risk.
The see-saw that matters
Here is the mechanism worth burning into memory. Suppose you hold a bond paying 7% and new bonds are now being issued at 8%. Nobody will pay Rs 1,000 for your 7% paper when Rs 1,000 buys 8% next door, so your bond’s price falls until its yield matches the new world. If rates fall to 6%, your 7% bond is suddenly premium paper and its price rises. The longer the bond’s maturity, the more violent the swing: a 10-year bond moves about 7% for each 1% move in rates, a 2-year bond barely 2%.
This is why people who “only buy safe bonds” still lose money. They buy a long bond fund, rates rise, the statement shows a loss, and they conclude bonds are risky. The bond did not get riskier; its price did what prices do. Held to maturity, you still get every coupon and the full face value back, assuming the borrower pays. The loss only becomes real if you sell mid-way.
What this means in practice
My rule of thumb is one question: will I hold this to maturity? If yes, buy the bond or the gilt fund matched to your horizon and ignore the daily price noise; your return was decided the day you bought. If no, you are a bond trader whether you meant to be or not, and you are making a bet on interest rates, which is a bet professionals lose regularly.
India’s investing conversation is so equity-obsessed that most people meet bonds only through a debt mutual fund’s bad quarter. That is a shame, because a bond is the most honest contract in finance: it tells you exactly what you will get, and asks only that you understand the price of leaving early.
Read: State development loans
Read: RBI Retail Direct
Equity asks “how much can this grow.” A bond asks “can you wait.” The answer to the second question is what decides whether the first one ever matters.