InvITs
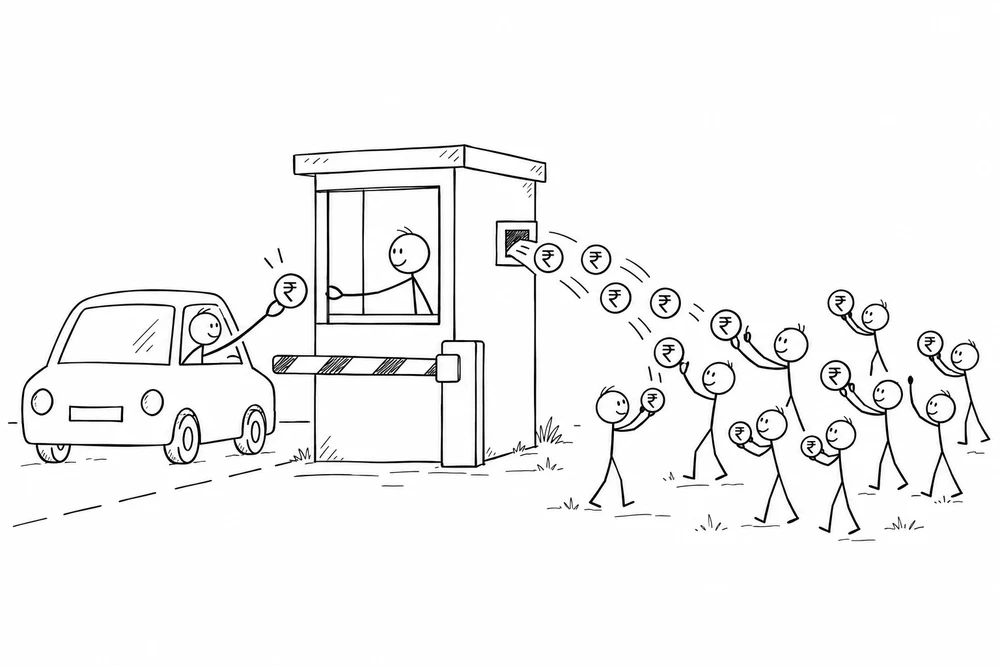
There is a stretch of highway between Mumbai and Pune where every car, truck and bus that passes hands money to a machine.
What an InvIT actually owns
An Infrastructure Investment Trust holds income-producing infrastructure: toll roads, power transmission lines, gas pipelines, telecom towers.
The 10% is not interest
This is the part the FD comparison gets wrong. The payout has three moving parts.
Who these suit
I think of InvITs as a product for someone who wants income now and can read a cash flow statement. A retiree who wants monthly-ish payouts and understands that part of the “yield ” is their own money coming home.
There is a stretch of highway between Mumbai and Pune where every car, truck and bus that passes hands money to a machine. Multiply that by seven toll roads, and you have the business of IRB InvIT, a listed trust that owns toll road concessions and pays the toll collections out to its unit-holders. In FY26 it distributed Rs 6.60 per unit; with units trading around Rs 65 in mid-September 2026, that is a cash yield of roughly 10% a year. An InvIT is the instrument that lets you own a slice of that toll booth.
Most people meet InvITs through a screener filter for high dividend yield, see 8-10%, and assume it works like a bank FD with a bigger number. It does not, and the difference is worth understanding before the yield sucks you in.
What an InvIT actually owns
An Infrastructure Investment Trust holds income-producing infrastructure: toll roads, power transmission lines, gas pipelines, telecom towers. The names you will see most on NSE are IRB InvIT (toll roads), IndiGrid (power transmission, India’s first listed InvIT), and PowerGrid InvIT (transmission lines sponsored by PowerGrid Corporation). NHAI has also been packaging highway stretches into its own trust, NHIT.
The assets run on long contracts. A toll road concession with NHAI might run 20-30 years. A transmission line earns a regulated tariff for 35. The cash coming in is therefore about as predictable as business income gets, which is exactly why these trusts can pay most of it out. SEBI requires an InvIT to distribute at least 90% of its net distributable cash flow to unit-holders.
The 10% is not interest
This is the part the FD comparison gets wrong. The payout has three moving parts. First, some of it is a return of your own capital: the trust amortizes its debt and hands you principal back, which is why the yield can look so fat. Second, the unit price moves. A 10% yield does not help if the unit drops 15% because traffic projections were rosy or interest rates rose and made the yield less special. Third, concession assets run down. A toll road with 12 years left on its concession is a wasting asset; when the concession ends, the road goes back to the government.
Tax adds another layer. Depending on its composition, the distribution is taxed at your slab rate as interest or dividend, and the repayment-of-debt portion is now taxable too. After tax at the 30% slab, that 10% headline yield lands closer to 7%.
Who these suit
I think of InvITs as a product for someone who wants income now and can read a cash flow statement. A retiree who wants monthly-ish payouts and understands that part of the “yield” is their own money coming home. An investor who wants infrastructure exposure without picking EPC contractors. They are not a growth product and not an FD replacement; the corpus is not guaranteed, and liquidity on the exchange can be thin when you want to exit a large position.
If you buy one, buy it like you would buy a toll road: ask how many years the concessions have left, how much debt the trust carries against them, and whether the distribution is being funded by cash the assets earned or cash the trust borrowed.
A toll booth is a wonderful business: everyone pays, nobody haggles, and the road does not go out of fashion. An InvIT is simply the cheapest ticket to stand next to one, provided you remember the ticket itself has an expiry date printed on it.