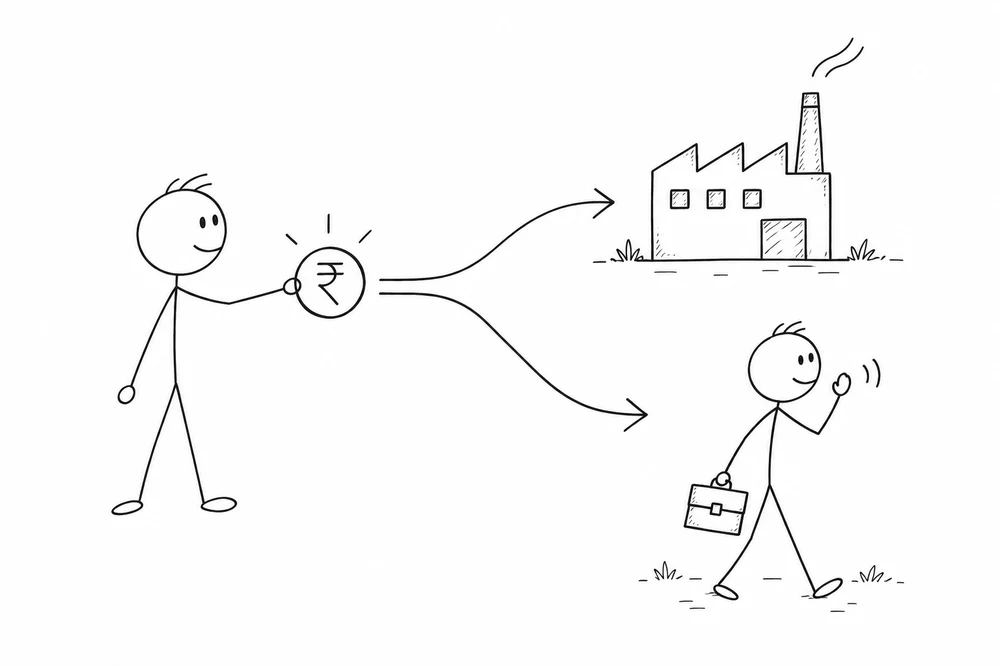
OFS vs fresh issue
In October 2024, Hyundai Motor India raised Rs 27,856 crore in India’s largest IPO ever. Not one rupee of it went to Hyundai Motor India.
Fresh issue: the company gets it
A fresh issue means the company creates new shares and sells them to you. The money lands on the company’s balance sheet and funds whatever the prospectus says: a new plant, debt repayment, working capital, an acquisition.
OFS: the seller gets it
An Offer for Sale means existing shareholders, the promoter, the PE funds, the early angels, are selling shares they already own.
Why the split matters more than the GMP
Take a Rs 1,000 crore IPO where Rs 700 crore is OFS . Whatever the grey market says, Rs 700 crore of the money raised is going to sellers and Rs 300 crore to the company.
The promoter signal
A PE fund selling is routine. The promoter selling a large chunk is information. Founders building a great business typically want to hold as much equity as they can.
For the fresh part, read the objects
The fresh issue portion comes with a section in the prospectus called Objects of the Issue: exactly what the company plans to do with your money.
How I use this
All-fresh-issue: the company needs you, alignment is clean, the only question is whether the business and price are good.
In October 2024, Hyundai Motor India raised Rs 27,856 crore in India’s largest IPO ever. Not one rupee of it went to Hyundai Motor India. The entire issue was an Offer for Sale: the Korean parent sold 17.5% of its stake and collected the cheque. A year later, LG Electronics India did the same thing, an entirely OFS issue of around Rs 11,600 crore.
Most people applying to these IPOs could not tell you this, because the first numbers they look at are the GMP and the subscription tracker. That is the beginner mistake. The first number worth looking at in any IPO is the fresh issue versus OFS split, because it answers the only question that matters on day one: who gets your money?
Fresh issue: the company gets it
A fresh issue means the company creates new shares and sells them to you. The money lands on the company’s balance sheet and funds whatever the prospectus says: a new plant, debt repayment, working capital, an acquisition. The share count goes up, existing shareholders get diluted, and the business gets fuel. This is the original, honest purpose of an IPO. A growing company needs capital, the public provides it, everyone is aligned.
OFS: the seller gets it
An Offer for Sale means existing shareholders, the promoter, the PE funds, the early angels, are selling shares they already own. The shares change hands, the company receives nothing, the share count stays flat. Your application money goes into the seller’s bank account.
To be clear, there is nothing automatically wrong with this. PE and VC investors have a lifecycle: they enter early, take risk, and at some point must return money to their own investors. An IPO is the natural exit. But you should know you are buying from someone who has decided this is a good time to sell. That is a different transaction from funding a company’s growth, and it deserves a different set of questions.
Why the split matters more than the GMP
Take a Rs 1,000 crore IPO where Rs 700 crore is OFS. Whatever the grey market says, Rs 700 crore of the money raised is going to sellers and Rs 300 crore to the company. The balance sheet improves by Rs 300 crore, not Rs 1,000 crore. When an issue is entirely OFS, like Hyundai’s or LG’s, the company raises nothing at all. It is a liquidity event dressed in IPO clothing. The businesses were strong and both listed fine, but nobody should confuse what happened with capital formation.
The question I always ask when I see a heavy OFS: why is the seller selling now? Sometimes the answer is benign, a fund at the end of its life. Sometimes it is less comfortable, growth has peaked and the insiders can see the valuation window closing. You cannot know which, but you can know to ask.
The promoter signal
A PE fund selling is routine. The promoter selling a large chunk is information. Founders building a great business typically want to hold as much equity as they can. When the founder or the founding family is the big seller in the OFS, I want to understand why. Personal liquidity and diversification are rational reasons. So is the belief that the business will never be valued this well again. The DRHP discloses the promoter’s holding before and after the issue. A promoter going from 70% to 35% in one IPO has told you something, whatever the roadshow said.
For the fresh part, read the objects
The fresh issue portion comes with a section in the prospectus called Objects of the Issue: exactly what the company plans to do with your money. The quality of this section varies wildly. A good one is specific: build this plant for this many crore, retire that loan, fund this much working capital, and you can check against annual reports later because SEBI requires companies to report on use of proceeds after listing. A bad one hides behind “general corporate purposes”, which usually means there is no plan, or no plan they want in writing.
How I use this
All-fresh-issue: the company needs you, alignment is clean, the only question is whether the business and price are good. Mostly-OFS: you are the exit, so the questions shift to who is selling, how much, and why now. Mixed: weigh the parts separately. This takes five minutes and changes how you read everything else about the IPO, including the subscription numbers everyone else is staring at. The sizzle is always louder than the substance. I wrote about this habit in the envy piece: we watch the GMP ticker and forget to ask who is on the other side of the trade.